
Borrowers restructuring their debts through Greece’s out-of-court settlement system could save thousands of euros under amendments to a Finance Ministry bill announced Tuesday, which would also sharply increase penalties for companies that manage loans.
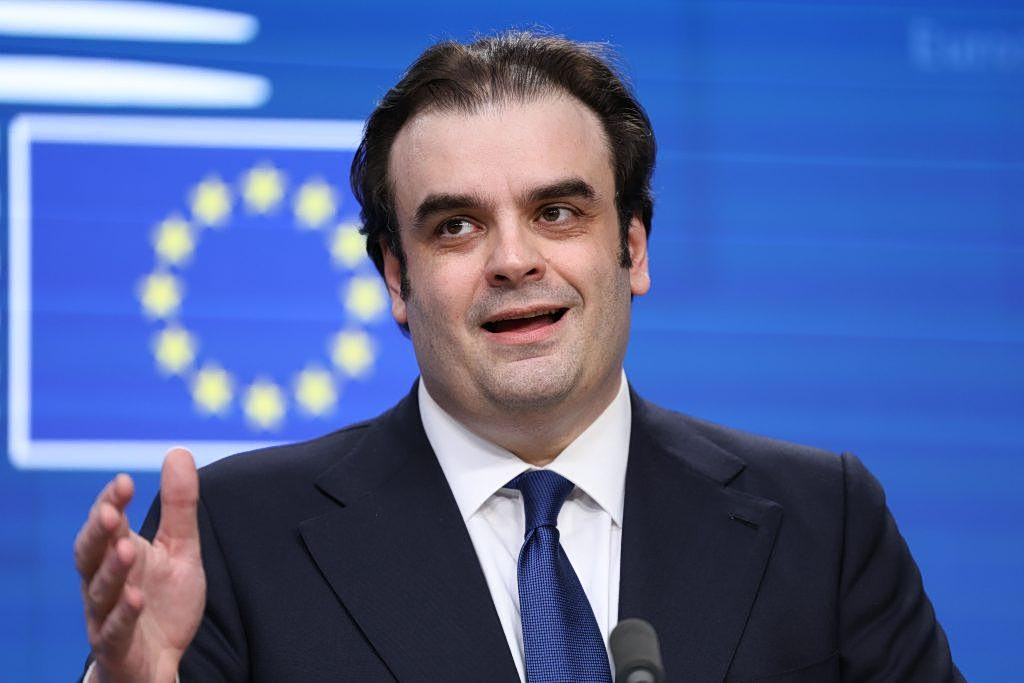
National Economy and Finance Minister Kyriakos Pierrakakis told a parliamentary committee that borrowers classified as vulnerable or eligible under the debt settlement system would pay a fixed interest rate of 3% for the entire repayment period, replacing a provision that limits the fixed rate to the first three years.
The changes are part of legislation on private debt and loan servicing companies that is due to be debated and voted on in Parliament on Wednesday, Nov. 4.
What Changes for Borrowers
Starting Dec. 1, 2026, the 3% fixed rate would apply for the full term of qualifying debt restructuring agreements, regardless of whether the debt is secured by collateral.
Under the existing rules, borrowers pay a fixed 3% rate for the first three years before switching to a variable rate. The amendment would make the fixed rate a mandatory part of the restructuring agreement.
Pierrakakis said the measure would allow borrowers to know how much they would need to repay over the life of the agreement, making it easier to plan their finances and keep up with payments.
For a debt of 100,000 euros repaid over 20 years, the minister estimated savings of approximately 20,200 euros on a secured loan and 28,600 euros on an unsecured loan.
Loan Servicers Face Higher Penalties
The Finance Ministry is also proposing a tenfold increase in the maximum fine the Bank of Greece can impose on loan servicing companies, raising the limit from 500,000 euros to 5 million euros. The penalties would apply to serious breaches of the companies’ legal obligations, including rules on how they deal with borrowers.
Loan servicers manage debts on behalf of creditors and have become a central part of Greece’s private debt market.
Pierrakakis said the increase was intended to strengthen oversight of the sector and provide greater protection for borrowers. He clarified that the proposed penalties would operate separately from those covered by Article 15 of the bill.
Dispute Over Withdrawn Provision
The amendments were announced as Pierrakakis defended the ministry’s decision to withdraw Article 23 of the legislation, which had drawn criticism from opposition parties. The minister rejected suggestions that the provision would have allowed loan servicers to pursue debt collection without adequate legal safeguards.
He said the article was designed to simplify the process of putting an existing agreement between a borrower and a creditor into effect. It would not, he argued, have allowed servicers to unilaterally make any loan legally enforceable, and borrowers would still have been able to challenge enforcement through the courts.
Pierrakakis accused opposition parties of misrepresenting the measure and said the ministry had withdrawn it to remove a point of contention.
He also criticized former Prime Minister Alexis Tsipras, pointing out that the regulatory framework for investment funds acquiring loans had been introduced under his administration. By the end of March 2019, while Tsipras was still in office, loan servicing companies had taken over the management of approximately 18 billion euros in loans, according to figures cited by the minister.
Pierrakakis also called for PASOK to put forward what he described as practical proposals on private debt rather than “resorting to political slogans.”
Source: tovima.com